Stocks Took the Soft Number. Bonds Gave It Back.The S&P 500 rose 0.74% to 7,723.49. The Nasdaq gained 1.19% after touching a record 27,353.68 intraday. The Dow added 0.49%, the Russell 2000 0.94%. The VIX eased to 15.31. Chips did the lifting. Nvidia (NVDA) touched an all-time high of $237.87. Only about 21% of S&P 500 members traded above their 50-day averages going into Friday, according to Charles Schwab. Bonds disagreed. The 10-year fell to about 5.16% after the 8:30 a.m. release, then closed at 5.28%, up 4 basis points. The two-year, the yield most tied to Fed policy, ended at 4.83%, up 5. It rose on a report that missed by more than half. TQ Trade Implication Equities priced a slower Fed. The two-year priced a Fed that still gets there. Next week brings three-year, 10-year and 30-year auctions on Tuesday, Wednesday and Thursday. Weak 10- and 30-year demand would say the long end's problem is supply, not the Fed. Carnegie didn't invent steel. He used new technology to produce it cheaper and faster than anyone on Earth. Rockefeller didn't discover oil. He used industrial machinery to refine it more efficiently. Vanderbilt didn't build the railroad. He understood that whoever controlled the infrastructure controlled the economy. Their combined fortunes were between $700 billion and $1 trillion. Best-selling financial author Alexander Green has identified three companies positioned to be the Titans of the AI age. CLICK HERE TO FIND OUT WHO THEY BEFORE THE WINDOW CLOSES October Faded. December Got Closer.Payrolls rose 29,000 in September, against the 84,000 economists surveyed by Dow Jones expected. July was revised to a loss of 10,000 and August cut to 133,000. Together, the revisions erased 60,000 jobs. Unemployment rose to 4.2%. Average hourly earnings grew 3.0% from a year earlier, the slowest since May 2021. That matches core PCE inflation through August, so the average worker gained nothing in real terms. Construction split. Nonresidential specialty contractors added about 12,000 jobs, residential ones shed about 7,900. Associated Builders and Contractors credited data centers. Kalshi's October hike contract fell from 28 cents to 13 in under two minutes. By early afternoon it was back at 19. CME FedWatch closed with October at 22.1%, from 24.4% Thursday. A week ago it stood at 64.2%. Most of October's repricing came before the report. December moved the other way. The odds of at least one increase by then rose to 86.3% from 79.8%. Dallas Fed President Lorie Logan said Thursday the range needs to rise "an additional 50 basis points or more." TQ Edge Setup The report changed the date, not the direction. Logan speaks Tuesday, and September CPI arrives in mid-October, before the Oct. 27–28 meeting. A hot print can pull the hike forward. A soft one leaves December carrying it. The G7 Will Release 100 Million Barrels. Diesel Believed It. Brent Didn't.After a videoconference convened by French President Emmanuel Macron, G7 leaders agreed to release 100 million barrels through the IEA over four months. A "frontloaded substantial diesel release" comes in the first 20 days. They also pledged to avoid energy export restrictions among members, the answer to a feared U.S. diesel export ban. Macron said Trump left no doubt there would be none. Heating oil futures, the U.S. diesel benchmark, fell 1.7%. WTI dropped 1.9% to $91.11. Brent fell to $98.43 intraday, then recovered to about $102.25, roughly flat. The release front-loads diesel. The statement doesn't split the rest between crude and fuel, or between new barrels and March pledges. That matches where the shortage sits. Crude through Hormuz is back near its prewar pace of 13.5 million barrels a day, Kpler data show. Fuel ran near 677,000, against 3.6 million before the war. Russia earlier this week kept its diesel export ban in place through October. TQ Edge Setup The IEA owes a follow-up report within 20 days, the same window the diesel barrels are meant to land. Watch the gap between heating oil and crude futures over those three weeks. It shows whether this is new supply or restated pledges. Wall Street veteran goes ALL in on Bank of Elon
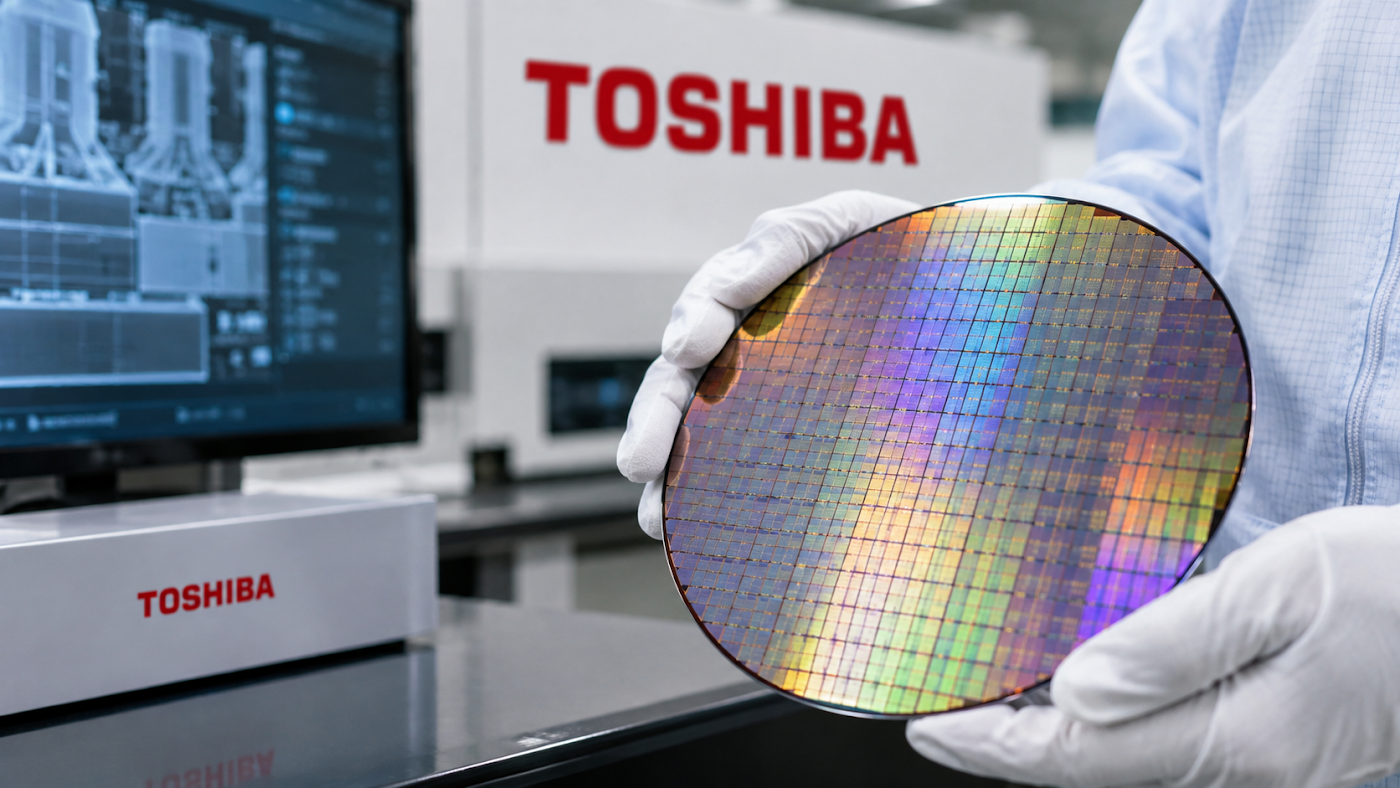
A 20-year Wall Street veteran – who worked at a $10 billion hedge fund – is putting ALL his money in Elon Musk's new bank. He says he can see the writing on the wall for traditional banks. And he's not the only one. See if you should join him here (not just for the 6% yield). This ad is sent on behalf of InvestorPlace Media at 1125 N. Charles Street, Baltimore, Maryland 21201. If you're not interested in this opportunity, please click here. The Drive Makers Sold Their Scarcity Premium. Nvidia Kept Its Bid.Seagate (STX) and Western Digital (WDC) each closed down 10.2%. Nikkei reported that Toshiba plans to double its data-center hard drive capacity within fiscal 2027. Toshiba will invest about ¥60 billion, roughly $380 million, in its Philippine plant. Three companies make the world's hard drives. Toshiba holds just over 10% of the market by capacity and is targeting 30% over the medium term, according to Nikkei. That share has to come from somewhere. Morgan Stanley and Citi kept positive ratings on both stocks. Morgan Stanley said the supply gap through 2028 still looks wider than Toshiba's addition. Nvidia closed up 1.3% the same day. Friday's news was about supply, not demand. TQ Execution Bias The tape split AI demand from component supply. Chip designers rallied on demand that is here now. Drive makers sold off on capacity due in fiscal 2027. Their next calls show whether forward pricing holds. - Tesla beat on cars, missed on storage. Tesla (TSLA) delivered 486,532 vehicles, 5.3% above its own compiled consensus. The stock rose 4.65%. Storage of 13.7 GWh missed the 15.9 GWh estimate. Deliveries topped production by 22,141, for a second straight quarter.
- Onsemi cut its Synaptics price and raised the payout. Onsemi (ON) switched to $123 a share in cash, about $5.7 billion, down from about $7 billion in June, after an unnamed rival approached Synaptics. At Thursday's onsemi close, the old stock terms were worth about $108. Synaptics (SYNA) closed up 14.1% at $121.10. Onsemi rose 6.0%.
- Blue Owl's exit line split in two. Withdrawal requests at Blue Owl's (OWL) flagship credit fund fell to 16.8% of shares, from 18.8% in the second quarter and 21.9% in the first. At its technology income fund, they held near 39%, where they sat last quarter. Both again capped repurchases at 5%, so a tendering flagship holder gets about 30% filled.
- Bitcoin made the round trip. Bitcoin topped $87,000 after the report, then slid to about $84,400 late in the day.
Middle East Conflict Lights Fuse on US Debt BombAmerica was already drowning in $38 trillion of debt, but the recent conflict in the Middle East just accelerated the timeline. As oil spikes, a 100-year-old stock market signal that accurately predicted the 2008 and 2020 crashes is flashing a massive "Sell" on dozens of popular U.S. equities. If you hold the wrong stocks when this debt crisis hits, it could wipe out years of gains. Click here to see the 10 popular stocks to dump immediately 11780 US Highway 1, Palm Beach Gardens, FL 33408-3080 Would you like to edit your e-mail notification preferences or unsubscribe from our mailing list? Copyright © 2026 Weiss Ratings. All rights reserved. Hike Bets Moved. Yields Didn't Follow.Friday gave the October trade its soft number. Kalshi's contract fell as low as 13 cents, and FedWatch ended October near 22%. It didn't deliver relief. The two-year finished at 4.83%, the 10-year at 5.28%, and December odds climbed to 86%. Stocks rallied anyway, on chips, with most S&P 500 members still below their 50-day averages. Next week's three auctions test which read holds. Solid demand lets the market keep treating the miss as good news. Weak demand says the long end is pricing something a payroll count can't fix. 3 STOCKS OUR SIGNAL ENGINE SAYS TO WATCH CAREFULLY Three stocks. Three signals. Two weeks later, the story changed.On September 2, we published three market questions around KLAC, HPE and PG&E.
Two weeks later, every one of them produced new evidence. One company delivered record revenue and raised its outlook.
Another saw weakness spread across its entire peer group.
And in the third, a market risk that had only been showing up beneath the surface suddenly became explicit.
Yet none of these stories is finished. That’s why we built Market Tell.
To track the signals that keep moving after the headline is gone — and show you what investors should be watching next. We’ve put the latest analysis into a new FREE Special Report:
3 Stocks at a Major Turning Point See what changed… what still hasn’t been resolved… and the signals we’re watching now. Get the Free Report → |
|